What is a hard money land loan?
A hard money land loan is a short-term loan secured by unimproved or underused land and underwritten by a private lender on the land’s value, its status and the borrower’s plan for it. It is different from every other loan on this site in one respect: there is no income. An apartment building pays its own interest; a parcel does not. The lender is therefore underwriting an exit rather than a cash flow, and the exit is either a sale or a construction loan that replaces the land loan when the building starts.
Banks rarely finance land because of that, and when they do the leverage is low, the borrower’s global financials are underwritten in depth and the timeline is long. Private lenders finance it because they can price the risk: a lower loan-to-value, a shorter term, a reserve for the carry, and a clear view of the plan and the exit. The result is that most land in transition, from a lot bought at auction to a site waiting on its final entitlement, is financed privately.
Property types
Vacant land
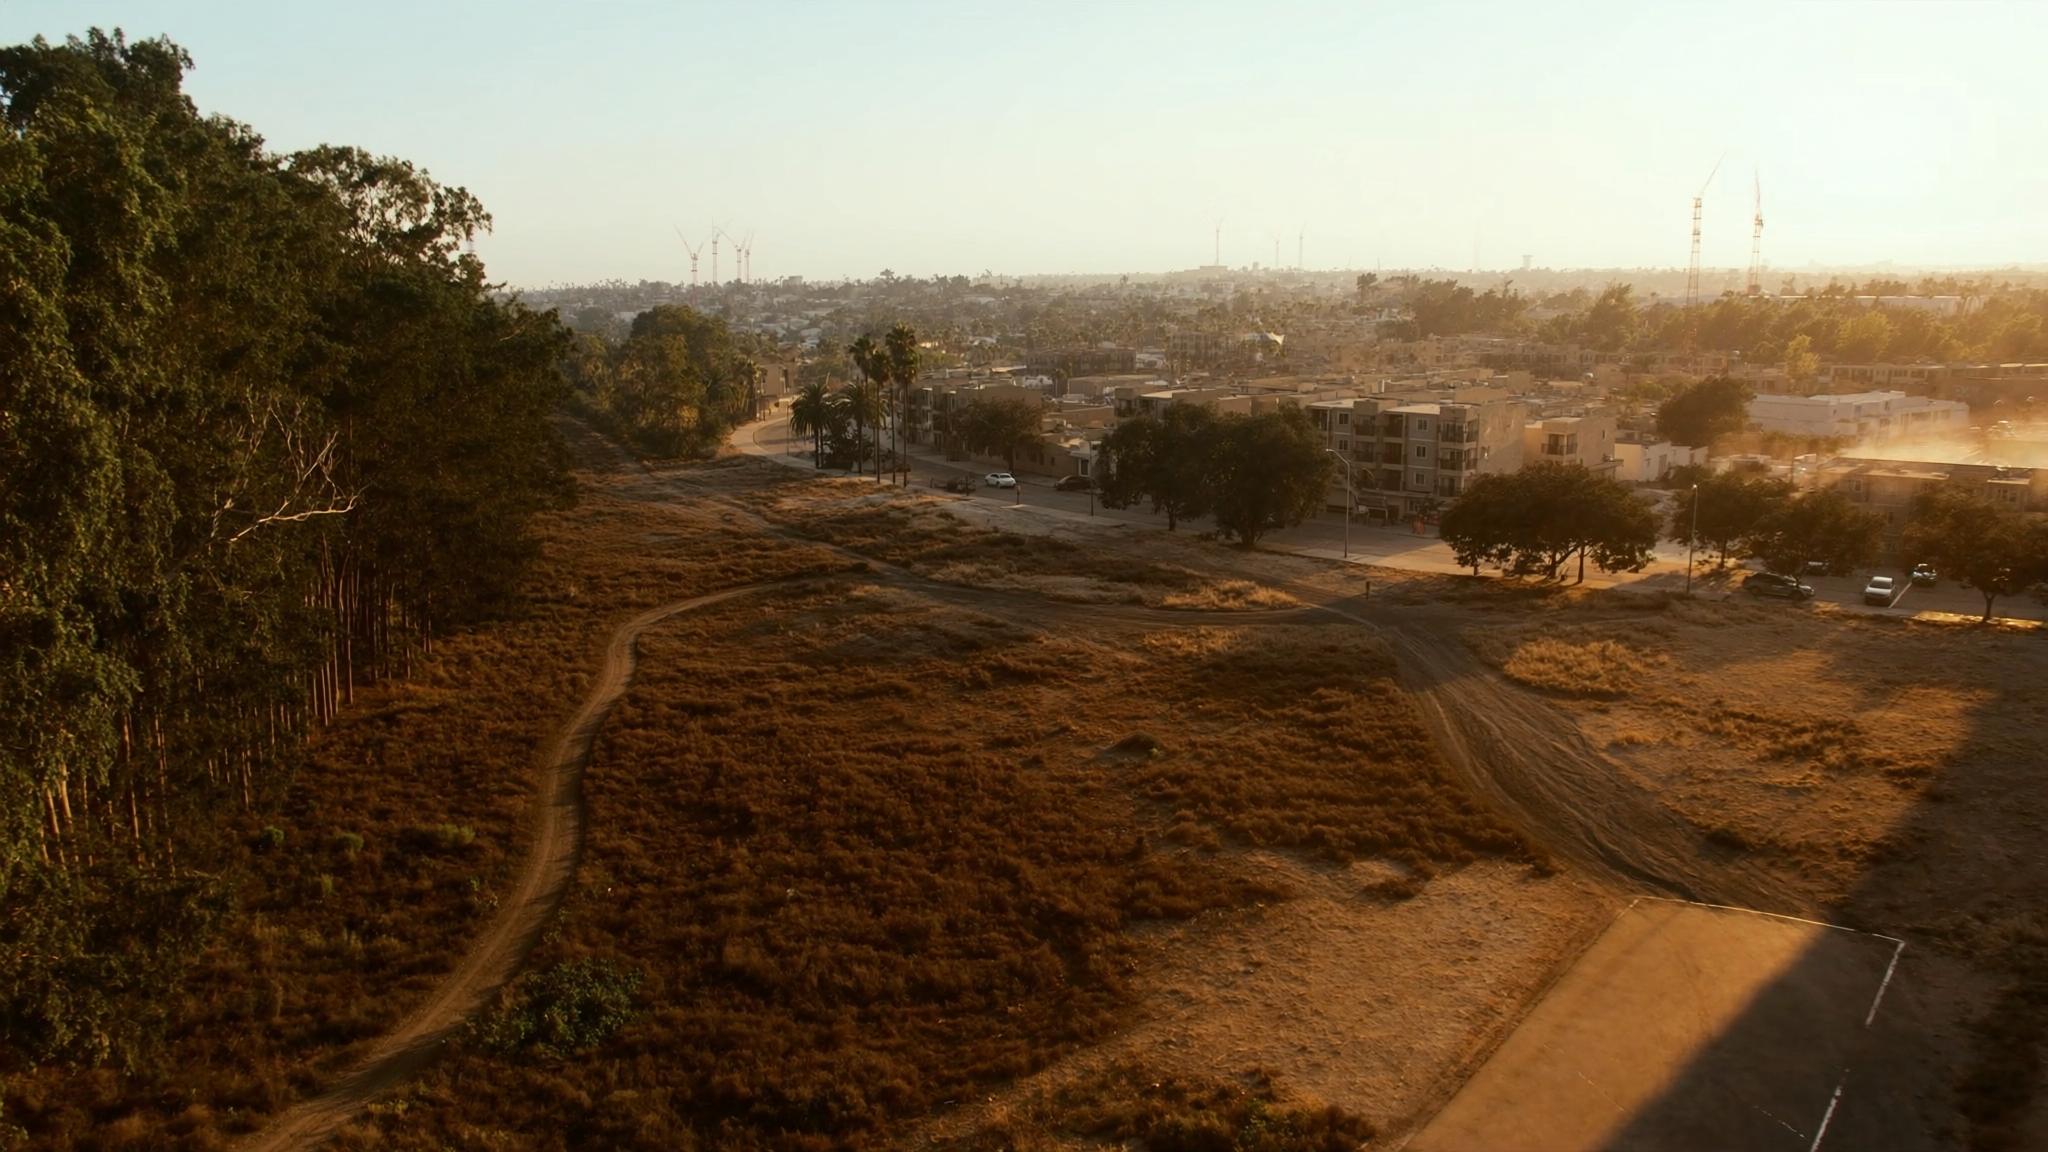
An unimproved parcel with no structures. It ranges from a single residential lot in an existing neighbourhood to acreage on the edge of a city. Value depends almost entirely on what can be built and when.
Infill lots
A vacant or teardown lot inside a built-up area, with utilities at the street and zoning that allows a house, a small multi-family building or a commercial use. The most liquid form of land, and the most common land collateral in hard money because the exit (a build or a sale to a builder) is close.
Covered land
Land with an existing income-producing use that is worth less than the land beneath it: a parking lot, an old strip center, a single storey warehouse on a corner zoned for density. The income carries part of the loan while the entitlement for the higher use is pursued. A parking lot is covered land in this sense: income today, a building tomorrow.
Land status
The single biggest driver of a land loan is how far the parcel has moved toward a building.
- Raw land. No approvals, often no utilities, sometimes no legal access. The longest road to an exit and the lowest leverage. Financed privately when the buyer has a plan and the equity to carry it.
- Entitled land. Zoning and approvals in place for a specific project, typically after a public process. The value has stepped up and the remaining risk is permits, financing and construction.
- Shovel-ready land. Entitlements, permits and utilities in place; construction can start. The land loan here is often a short bridge to the construction loan, or the land is folded into the construction loan itself.
Between these stages sit the situations private lenders see most: a parcel bought before the entitlement is complete, a lot bought at a foreclosure auction or an online auction for cash, and a builder who needs to close on a lot before the construction financing is arranged.
Why investors use hard money on land
- An auction purchase. Lots bought at a trustee’s sale or online are paid for in cash on a short clock; a land loan replaces the cash so it can be redeployed.
- An entitlement bridge. The parcel is bought before the approvals are final, at a price that reflects the uncertainty, and held on a private loan through the public process.
- A builder’s lot acquisition. A builder closes on a lot now and arranges the construction loan afterwards; the land loan is repaid when construction financing closes.
- Assemblage. Several adjacent parcels bought one at a time toward a larger site, each on a short loan until the assemblage is complete and the whole can be financed.
- A seller carryback that has matured. A seller-financed lot whose note has come due is refinanced privately while the buyer finishes the plan.
Pricing and terms
Land is priced on five things: the status of the parcel, the leverage requested, the size and location, the borrower’s plan and equity, and the exit. Leverage rises with entitlement status and falls with the time to an exit, and lenders lean on the lower of the purchase price and the appraised value. A reserve for interest is common because there is no income to pay it, and the term is set to the entitlement or construction calendar rather than to a lease-up.
Loan Goat prints its terms on product cards and this page repeats only those. The one published card that names land is the hard money commercial bridge, whose property types read retail, office, industrial, multifamily, mixed use, land, on the bridge program’s terms: one or two years, LTV up to 70% on commercial property, loans from $150,000 to $25,000,000, rates from 9.00% to 13.00%, a 650 minimum credit score, and a close in as quickly as 3 days on a clean file. The full card is printed below the article. That is the published ceiling, not a promise on any parcel: leverage on a specific piece of land is decided per deal and is not the same for raw land, entitled land and a shovel-ready lot. For the build that follows, the ground-up construction program publishes terms of 12 to 18 months and LTC up to 80% including the lot, the build and the interest reserve, on SFR, condo or townhome and 2-4 unit projects, with an experience requirement of 2 ground-up projects.
Points, fees and the rate on a specific parcel are quoted per deal. Rates and pricing are subject to change without notice and are not a commitment to lend; the pricing guide explains what moves a quote.
Requirements
- The parcel. A legal description, a survey, the zoning and general plan designation, utilities and access, any environmental or geotechnical reports, and the status of every entitlement.
- The plan. What will be built or sold, the budget, the schedule and the source of the construction financing.
- The borrower. Equity in the purchase, liquidity for the carry and the soft costs, credit in line with the program the request is routed to, and experience with comparable projects where a build follows.
- The exit. A sale contract, a builder’s letter of intent, a construction loan term sheet or the equity to build.
Exit strategy
A land loan is repaid two ways, and the lender wants to know which before funding.
- Sale. The parcel is entitled and sold to a builder or a developer at the stepped-up value, or an infill lot is sold to an end user. The sale can feed a 1031 exchange into the next parcel.
- Refinance into a construction loan. The land loan is paid off, or rolled in, when construction financing closes. On a residential project the ground-up construction program is the published route; on a commercial project the construction loan is arranged per deal.
Where land fits at Loan Goat
- Construction loans for the residential build that follows the land.
- Bridge loans for the hard money commercial bridge, the one published card that names land.
- Industrial and warehouse and multi-family for the buildings most parcels become.
- Auction.com and Hubzu for lots bought online.
Conclusion
Land is a bet on what comes next, and a land loan is priced on how close that next thing is. Send the parcel, the entitlement status and the plan, and Loan Goat will tell you whether it fits a program and what it would take to close.